A Northwest CU Saves $1M+ by Joining the CU Benefits Alliance
The top-performing credit union made a strategic transition to the CU-exclusive health plan, resulting in significantly lower expenses and industry-leading employee retention levels.
This Pacific Northwest credit union is used to being among the best. Its assets increase at roughly twice the industry average, and its membership is growing at about two and a half times that of the average credit union. But there is one area where the credit union continuously struggled. Despite pouring hundreds of thousands of dollars into its fully insured health plan each year, employee premiums, copays, and deductibles kept rising to unsustainable levels without any tangible improvements in plan quality to justify the escalating costs.
The credit union’s President and CEO knew it could do better by its employees and its member-first mission. With health insurance among its top three expenses, he wanted health plan performance at the same level of excellence as the credit union’s top-tier Return on Assets (ROA).
Challenge
The credit union was losing staff to employers offering more competitive healthcare plans as its insurance expenses continued rising at unsustainable rates without any improvements in plan quality.
Outcome
By joining the CU Benefits Alliance, the credit union dramatically lowered its employees’ share of healthcare expenses and the credit union’s per-employee costs while experiencing a substantial improvement in the quality of the health plan.
Impact
The now-affordable health plan continues to see extensive savings with much higher participation rates. As a member of The Alliance, the credit union now has access to strategic insights and superior service that can mitigate the need for future cost escalations.
From the employee perspective, what
President and CEO, Pacific Northwest credit union
we’ve been able to do through our work
with The Alliance is deliver a far superior
benefits package at a lower cost to
employees and achieve cost savings
on the credit union side. It’s really been
a win, win, win for all of us. Our
employees have better benefits for
lower contributions than six years ago.
And the credit union, our growth
and expense has certainly been well
below medical trend over that time.
Challenged by adverse selection and
rising costs
Enrolled in a traditional health insurance plan through one of the nation’s largest health insurance providers, the credit union struggled to manage the cost of benefits. No matter the adjustments the credit union made to take on a larger portion of expenses, the employee contribution in the form of premiums, copays, and deductibles increased substantially each year.
“It became almost hopeless for our employees,” says the CEO. “They would pay all this money for health insurance, but they still had a deductible that would cause a significant financial hardship for them.”
Soon, the credit union found itself with an adverse selection problem. Young, healthy employees decided it wasn’t worth the cost to join the company’s healthcare plan, even for those with young children. “We were left with this exposure to a non-standard health group because of how much it cost for benefits and, frankly, how poor the benefits package was for the employees,” says the CEO.
In 2018, the credit union took action to reduce costs, improve plan quality, and raise participation rates.
Embracing a new plan
The credit union started by partnering with the Credit Union Benefits Alliance (The Alliance) to transition away from its fully insured plan to a partially self-insured option where the company had a single point of contact for its plan administrator (TPA), network, and high-claims insurance (reinsurance).
After a couple of years of seeing expenses trending in the right direction, the credit union took further control by segmenting out its reinsurance and TPA. The move carved out even more cost savings thanks to an exclusive 8% discount off standard billed charges at the region’s major healthcare provider. That relationship alone accounts for about 60% of the credit union’s medical care spending.
“The latest iteration was really fantastic,” says the CEO. “Thanks to The Alliance and our TPA, we negotiated the additional discount with our one major provider. That allowed us to dramatically improve the benefits and create a preferred network with the large provider.”
With the employee deductible down to a manageable $250 and co-insurance down to 5%, employees who had turned down the health plan in the past started to rejoin and bring their children with them. The younger demographic further balanced the credit union’s risk exposure.
A solution fit for leading credit
unions
Knowing healthcare expenses account for a substantial portion of a credit union’s expenses — and grow anywhere from 15%-20% a year — the CEO appreciated The Alliance’s philosophy of treating a health plan just like any other part of the business that must be managed for quality and performance. “The Alliance provides the leadership and insights we need to apply innovative strategies that improve the benefits and provide a lower cost,” says the CEO. “I think of it the same way as any other investment we would make in a member service or an efficiency technology.”
With a strong finance background, the CEO prioritized observing how money flows through The Alliance health plan and quickly determined the credit union was “likely to save quite a bit of money,” he says.
The credit union took full advantage of its position in The Alliance, the only credit-union-exclusive healthcare partnership in the country. Unlike traditional set-it-and-forget-it health insurance coverage, The Alliance closely tracks plan utilization to optimize its members’ experience continually.
“Working with The Alliance, we get a monthly recap of what types of claims are coming in and how we are running in relation to our expected costs,” says the CEO. “Then, we do an annual utilization review and try to adjust how the plan
is delivered so we can drive participants to the best-cost program and ensure they’re able to get the care they need in a way that’s also the most fiscally responsible.”
The Alliance’s active plan management gives the credit union more visibility and influence on its health plan than ever.
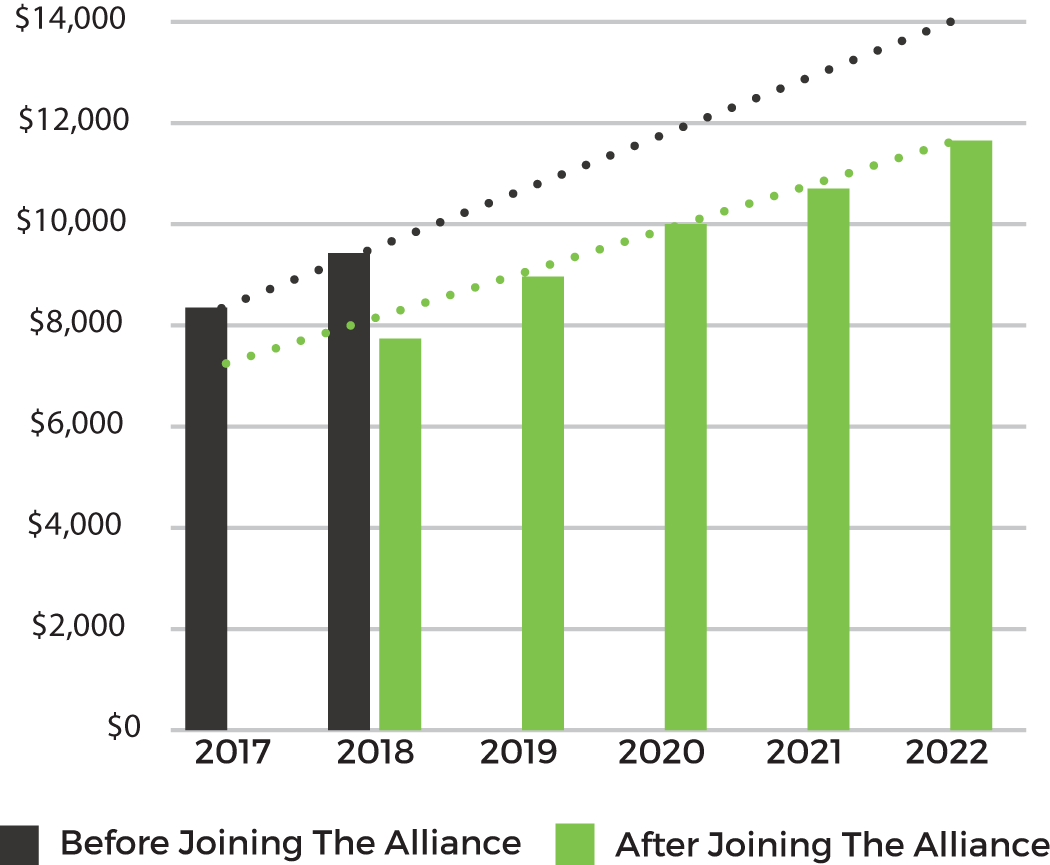
Annual Employee Medical & Prescription Costs
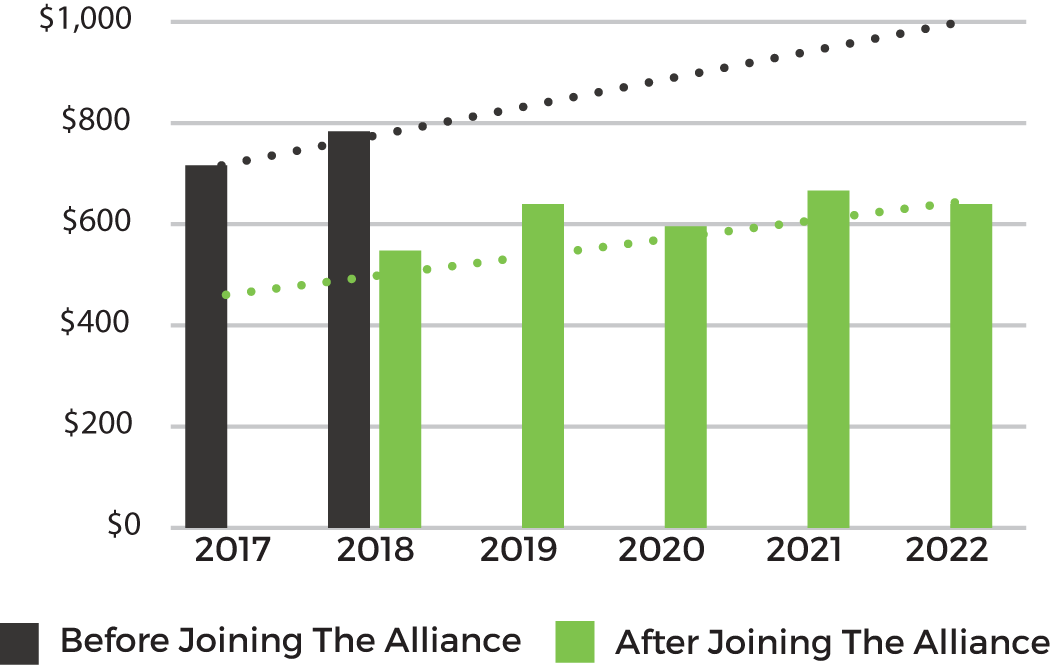
Annual Employee Dental Costs
Undeniable results
Being part of the coalition of credit unions, with its younger and healthier populations, is paying off. “Having actuarial experience specific to credit union group benefits us,” says the CEO. “Since coming off our traditional health plan in 2017, we’ve looked at the medical trend rate to compare what we would have paid versus what we are actually paying. It’s a staggering gap that definitely contributes to our ROA.”
He adds, “Over five years, we’ve likely saved over a million dollars compared to a traditional plan that would’ve been going up 15, 18, 20% per year. And, we’re one of the smaller headcounts in The Alliance. So I suspect that cumulatively around the group, millions of dollars of cost savings have resulted from participation in The Alliance.”
Specifically, the credit union recently saved $1,320 per employee per year (PEPY) over its expected costs from the prior year. The credit union also received a share of over $2 million in a return of unused premiums from being part of The Alliance the past two years.
Employee Share of
Healthcare Expenses
Quality of
Healthcare Network
Employee Plan
Participation
The Credit Union’s
PEPY Costs
Values-driven employee engagement
In addition to the financial savings, the credit union weaves its core values into the health plan. One is operational simplicity. “Our health plan is a good reflection of that,” says the CEO. “We want it to be very simple for our employees so that it produces an operationally simple experience for the end user.”
That operational efficiency goes hand-in-hand with another leading value: employee experience. The credit union is a two-time top workplace winner with a very high employee engagement score and an employee-net promoter score of 95. “I see our health benefits package as part of the reason we have those ratings,” says the CEO.
Yet another satisfaction indicator: All of the credit union’s branch managers have been with the credit union for at least five years, including no turnover during the pandemic turmoil. Additionally, at a roughly 16% annual employee turnover rate overall, the credit union has about half the industry average of 30%.
“Our health benefits package was not competitive before we teamed with The Alliance. We were losing employees to county, state, and federal jobs because they could get better benefits. We’ve worked really hard to manage our plan so that we can be competitive enough that people will choose to stay or come here,” the CEO says. “And now, we are competitive — even with the public employers.”
Unparalleled thought leadership and support
In addition to the straightforward cost savings, the CEO believes the cooperative nature of credit unions magnifies the benefits of being in The Alliance. The collaborative environment fostered by the credit union-exclusive group facilitates creative thinking about emerging healthcare trends and issues that could present significant expenses.
“Working together, we are discussing strategies to manage the expense of emerging therapies or million-dollar treatments on the rare occasions when they come up,” says the CEO. “We’re being proactive so that we will have a plan for these things that aren’t necessarily on the radar of other credit unions right now. It’s imperative to have a strategy to address these emerging issues. That’s the kind of thought leadership strategy we get from working with The Alliance.”
As for day-to-day plan management, The Alliance consistently delivers. “The support we get from The Alliance is almost unheard of,” the CEO says. “We have vendors, and we have partners, and The Alliance is very much in the latter of those categories. It’s one of the highest service levels we see. And they’re also just really good people. Super high integrity professional, friendly, responsive, all you would want your business partner to be.”